Taxing AI to save workers would hurt them
For half a century, advanced economies systematically lowered taxes on savings and investment to raise productivity and wages. Concerns about the growth of artificial intelligence may be unwinding that consensus among some pundits and policymakers.
For example, a widely read Wall Street Journal column argues that the answer to AI fears is to tax capital more heavily.
The argument starts with the assumption that large-scale job displacement is likely and that income will shift away from workers to owners of capital. More than 200 economists and AI researchers, including 16 Nobel Prize winners, endorsed this view in a recent letter. These arguments are largely unfounded. Labor has not been systematically losing ground, and AI is less likely to change that than many people think.
The second part of the argument is that the tax code already favors capital over labor, accelerating the economic shift to machines. This premise is also wrong, and worse, it could lead to even more destructive taxes: Once policymakers decide that taxes on profits do not capture enough of AI’s supposed value, the next step is to tax revenue itself.
Is capital undertaxed?
Economists Daron Acemoglu, Andrea Manera and Pascual Restrepo have quantified the popular narrative that the tax code already overtaxes labor and undertaxes capital. They estimate that in the United States labor faces an effective tax rate of around 25 percent while equipment and software face rates closer to 5 percent. The gap looks damning, but it is mostly a matter of timing.
Take the U.S. as an example. On the business input side, wages are 100 percent deductible the year they are paid. Most physical investments get the same treatment. Under the 2025 tax package, equipment, research and development, and manufacturing structures are eligible for immediate deductions and are at parity with labor. The acceleration of these deductions following changes in the law artificially depresses the Acemoglu-Manera-Restrepo calculation. Non-manufacturing structures are still disfavored in the U.S. and must be depreciated over three to four decades. So, on this margin, there is no systematic bias toward capital.
The only significant tax asymmetry that remains in a firm’s decision between capital and labor is the payroll tax. Economists generally assume that the economic cost of this tax falls not on a firm’s owners, but overwhelmingly on workers themselves through lower take-home pay. Given equal outputs, firms compare total compensation costs – including any payroll levies − to total machine costs. If payroll taxes are largely capitalized into wages, the tax is not a penalty on firms employing humans.
The same logic applies to the output side, where the relevant comparison is between the taxes that distort employees’ decisions to work and savers’ decisions to invest. Labor income is taxed by income and payroll taxes. In the U.S., the Treasury Department estimates the average federal tax rate on labor at 17 percent. The top federal marginal statutory rate is 40.8 percent.
The return on invested capital in public markets is subject to taxes at the entity and investor levels in most countries. In the U.S., corporate profits are taxed at the federal rate of 21 percent, and the remainder is taxed again at rates up to 23.8 percent when paid out as dividends or realized as capital gains. Combined, the top statutory federal tax rate is roughly 40 percent on the return to corporate equity. Average effective tax rates on investment differ by business form and financing source, but generally fall between the 25-35 percent range.
However, the economic burden of the tax matters more than the income stream the rate is applied to. Capital taxes fall largely on workers because they reduce investment, slow productivity growth and lower wages. One recent review of the research implies that a 1 percent increase in capital per worker raises wages by about 3 percent. Raising taxes on capital will reduce its deployment, hurting workers who need newer, better tools to keep up in our rapidly changing economy.
When profit taxes are not enough
The argument for higher capital taxes is only the first part of the debate. Early-stage AI firms and the big hyperscalers are spending huge sums on their infrastructure buildouts. They deduct that spending and many currently report little taxable profit. To critics, low or zero profits look like evidence that the income tax is failing to capture important economic activity.
Europe has already seen a form of this argument. Policymakers decided corporate income taxes were not taxing large technology firms heavily enough. Instead of reforming income or consumption taxes, several European Union countries designed new revenue taxes on “digital services.” These taxes apply whether or not a company earns a profit. The European Commission’s proposal for a bloc-wide tax on such services, however, remains stalled.
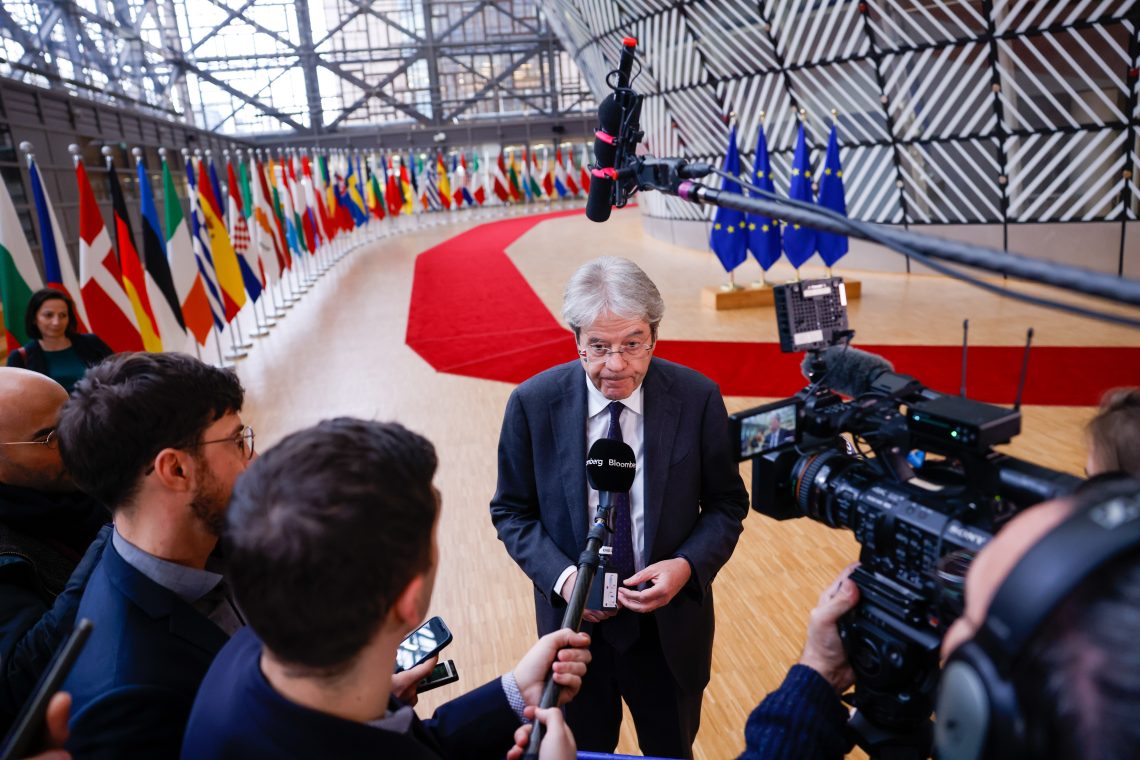
The same logic has now spread to the debate over AI on both sides of the Atlantic. Pasquale Tridico, chair of the European Parliament’s tax subcommittee, floated a new undefined tax on artificial intelligence. U.S. Senate Finance Committee Ranking Member Ron Wyden recently proposed a new gross-receipts tax on operators of U.S. data centers.
FACTBOX: Special taxes on technology in the EU
Digital services taxes (DSTs), which apply to revenue whether or not a company earns a profit, are in place at the national level in some European countries but are still being discussed at the EU and global levels.
In place
-
-
- France, Italy and Spain levy a 3% tax on gross digital services revenue, and Austria levies 5% on online advertising revenue. The taxes usually apply to large multinationals with global revenues over 750 million euros and a minimum level of digital revenue in the country. Poland taxes streaming revenue and Hungary taxes advertising revenue, but the rate is currently set at zero.
-
Proposals
-
-
- Belgium, the Czech Republic, Germany and Poland have proposed or considered implementing their own national digital levies but have not yet enacted them.
- Bloc-wide DSTs have been proposed, most recently in June 2026, but Brussels has not implemented them due to lack of unanimity and pushback from Washington.
- Member of the European Parliament Pasquale Tridico’s proposal to tax AI argues that the technology generates output and value similar to those of a human worker or corporate capital, making it a logical subject for taxation. He links the proposal to Europe’s aging population and the risk of AI displacing both manual and white-collar jobs, which threatens to shrink traditional tax revenues. He also notes that the heavy electricity demand from AI’s large-scale data center infrastructure will drive public expenditure that must be financed. Mr. Tridico has yet to elaborate on the specifics of such a tax.
-
If the Wyden proposal passed into law, it could push effective tax rates above 100 percent in several of the U.S. counties with the most data centers. Because the burden of revenue taxes increases as margins get thinner, these taxes hit new entrants and marginal projects that competition depends on the hardest.
A tax on compute, tokens or energy has the same flaw. Taxing intermediate inputs raises taxes unevenly, is disconnected from the ability to pay, and pyramids through the production process, making it one of the most damaging ways to raise revenue.
None of this is needed for tax systems to capture the gains that will come from AI investments. If AI earns the large profits its advocates predict, existing corporate and capital income taxes will capture them. To secure tax revenues while encouraging economic activity, policymakers can move toward a tax base that exempts the normal return to saving and taxes above-normal returns at the same rate as wages. Short of that, they could protect full expensing and reject revenue-based taxes entirely.
Scenarios
Most likely: Countries diverge on taxing AI
Some countries concerned about AI’s effects on labor markets, primarily in Europe, respond to public anxiety with taxes on compute, revenue taxes on data centers or higher taxes on corporate profits and capital gains. Others follow the recent lead of the U.S., the United Kingdom and Canada, which have all expanded immediate deductions for investment, and compete for global AI and AI-enabled investment. Some data centers need to be in close proximity to end users, but other key training and building investments are more mobile.
This marginal investment will move toward low-tax, reliably governed jurisdictions. Countries that hold back from taxing AI, including the U.S. if it keeps current law, gain the most from productivity growth and the higher-paid jobs that come with it. Higher-tax countries will pay more for AI services built elsewhere, and will fall behind economically.
Less likely: No policy action
Political pressure fades as it becomes clear that labor markets will gradually adjust to AI, and the doom scenarios seem more far-fetched. Current tax rules stay in place, full investment deductions survive and international tax competition continues to keep taxes on marginal capital relatively low.
Least likely: A global agreement on taxing AI
Governments worldwide agree on a common approach, such as a coordinated minimum tax or a shared compute levy, to prevent AI investment from moving to lower-tax countries. The clear failure of the OECD’s global minimum corporate tax under the inclusive framework suggests little chance of success. A tax agreement on a fast-moving technology would face the same problems and competing incentives worldwide.

Our Partners